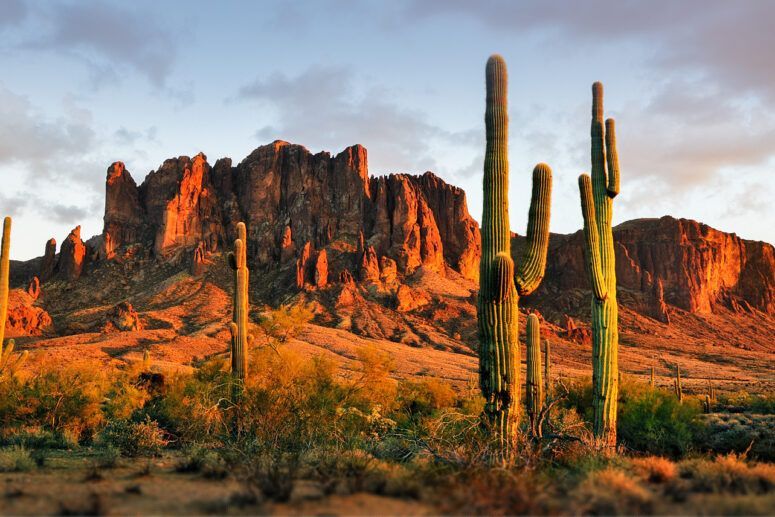
If you've been searching for a home in the East Valley of Arizona, you've probably spent some time looking at Mesa, Gilbert, Chandler, or Queen Creek. But there's another community that I think deserves a closer look: Gold Canyon. And if you've never driven through Gold Canyon, you might be surprised by what you find. Those Mountain Views Are Hard to Beat One of the first things you'll notice about Gold Canyon is the Superstition Mountains. They're not just something you occasionally catch a glimpse of in the distance. In many neighborhoods, those mountains are the backdrop to everyday life. And there's something about that scenery that makes the area feel more open. Even in neighborhoods where homes are relatively close together, the mountain views, desert landscape, and surrounding open spaces can give you the feeling that you're not living right on top of your neighbors. Of course, not every property has the same views or privacy. Some homes back to other houses, while others border desert areas, washes, or common spaces. That's why I always encourage buyers to look beyond the interior of a home and pay attention to what's around it. You can change your flooring or remodel your kitchen. You can't move the mountains or change what's behind your backyard. But Isn't Gold Canyon Far From Everything? Let's address the elephant in the room. Gold Canyon isn't Gilbert or Chandler when it comes to the number of restaurants, shopping centers, and entertainment options right outside your neighborhood. And for some buyers, that's going to be a dealbreaker. But here's what I think people sometimes overlook. Gold Canyon has everyday conveniences, including grocery shopping, restaurants, and local services. And when you're looking for a wider variety of dining, major retailers, or additional shopping, many options in the Apache Junction and east Mesa areas are roughly a 15- to 20-minute drive away, depending on where you live and where you're headed. That means you can enjoy the quieter desert setting without necessarily giving up access to the things you use regularly. Now, if you're someone who wants dozens of restaurants within five minutes of your front door, Gold Canyon may not be the right fit. But if you don't mind driving a little farther for more choices, the trade-off might be well worth it. A Different Kind of Arizona Lifestyle Another reason buyers are drawn to Gold Canyon is the outdoor lifestyle. You've got hiking opportunities, desert scenery, and golf courses, including Dinosaur Mountain and Sidewinder at Gold Canyon Golf Resort, along with Mountain Brook Golf Club. And unlike some of the busier parts of the Valley, Gold Canyon has a setting that can make coming home feel a little different. That doesn't mean every neighborhood is secluded or every street is quiet. It means buyers have an opportunity to find a home in a community where the natural surroundings are a major part of the appeal. For buyers relocating from other states, particularly those who've spent years dealing with cold winters, that desert landscape can be a big part of why Arizona is so attractive in the first place. You Might Get More of What Matters to You When buyers compare homes, it's easy to focus entirely on square footage, bedroom count, and price. But I encourage them to consider the things that don't show up as easily in a property search. What's the view from the backyard? How close are the neighboring homes? Does the lot back to another house or an open area? How does the neighborhood feel when you drive through it? Those details can have a huge impact on how much you enjoy living in a home. Gold Canyon has properties ranging from smaller, low-maintenance homes to larger homes with pools, outdoor entertaining areas, and beautiful mountain settings. And depending on the neighborhood and current market, buyers may find features here that are harder to get at the same price in other East Valley communities. That doesn't mean every Gold Canyon home is a bargain. It means the location deserves to be part of the comparison. So, Is Gold Canyon Worth Considering? I think it absolutely is, especially if mountain views, desert scenery, and a little breathing room are high on your wish list. But I also think it's important to be realistic about the trade-offs. You'll have fewer nearby shopping and dining choices than in some of the larger East Valley cities, and your daily drive matters. My advice? Before you rule Gold Canyon out because it looks a little farther away on a map, take an afternoon and explore it. Drive through a few neighborhoods, stop for lunch, and see how long it actually takes to reach the places you'd use most often. You might discover that those extra few minutes in the car are a pretty reasonable trade for the scenery you get to come home to. Curious What a Home in the Mid-$600,000s Looks Like in Gold Canyon? We've got a great example to show you! Take a look at this beautiful single-story home we have listed in Gold Canyon. It offers 4 bedrooms, 3 full bathrooms, a separate office, and a gorgeous backyard with a pool and outdoor kitchen. But what really makes this property stand out is its oversized cul-de-sac lot, mountain views, and the open space beside the home that gives you that extra breathing room we've been talking about. Clich here to watch our full Youtube tour and see what Gold Canyon living could look like for you: https://www.youtube.com/watch?v=-VPpbRMeFcY
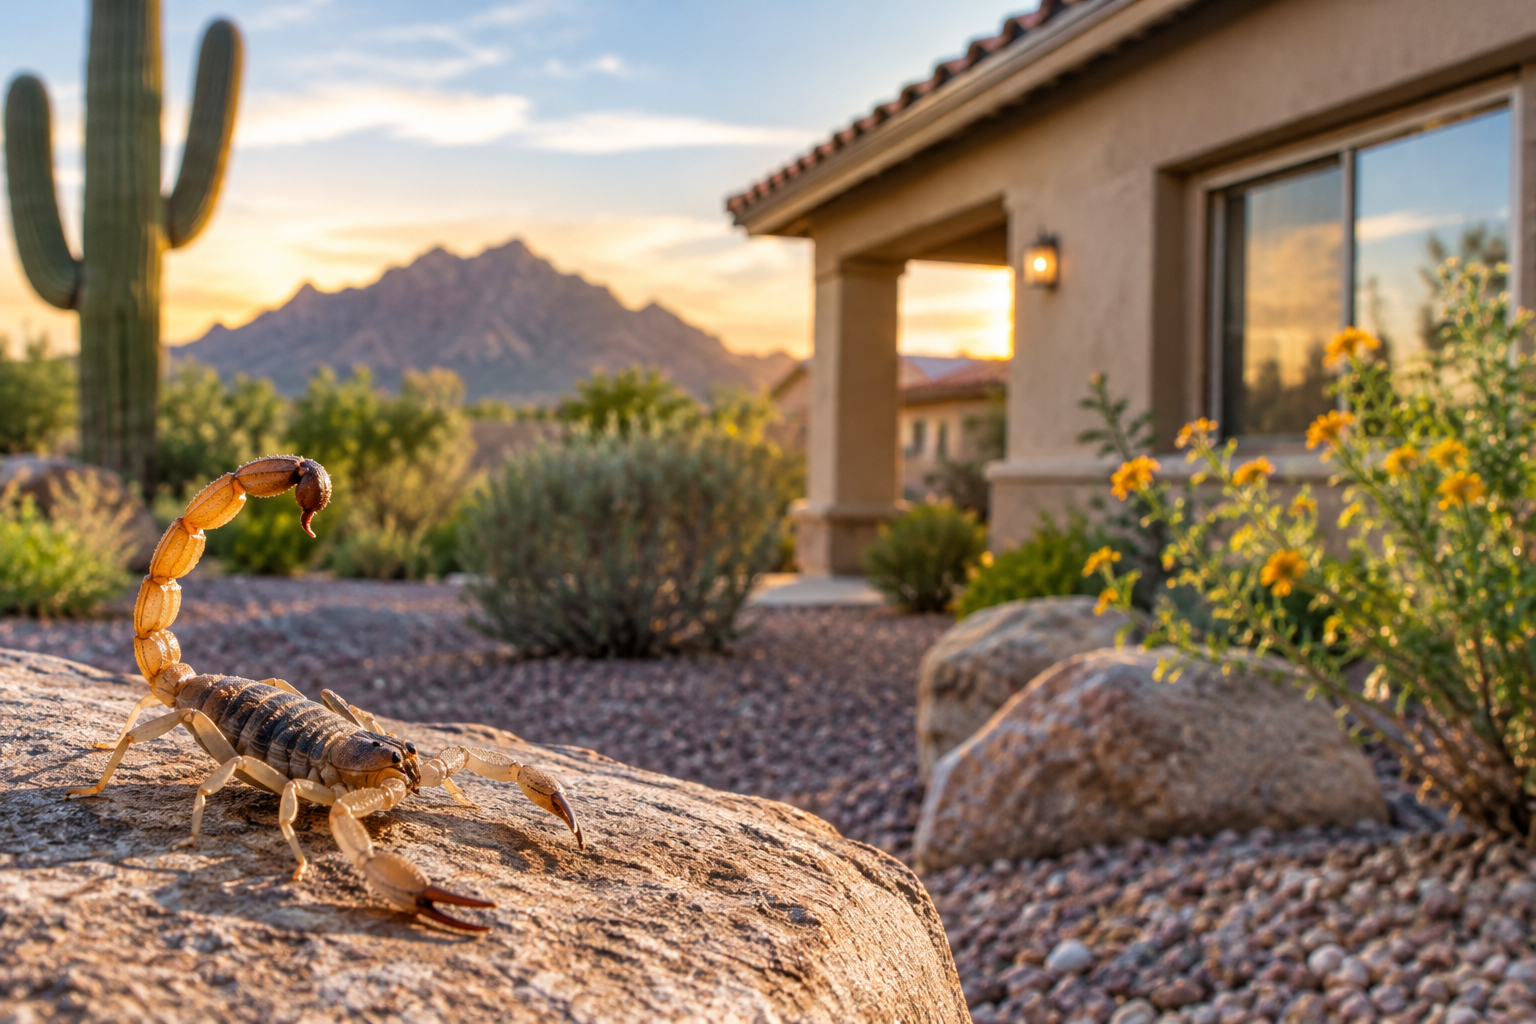
If you're buying a home in Arizona, especially if you're moving here from another state, there's a good chance you've asked this question: How often should I have my home sprayed for scorpions? Scorpions are one of those things that can make people nervous about living in the desert. And if you have small children crawling around on the floor or pets exploring the backyard, that concern is certainly understandable. The good news is that there are ways to help control scorpions around your home, and not every Arizona property has a scorpion problem. How Often Should You Treat Your Home for Scorpions? Many Arizona homeowners have their homes treated monthly or quarterly, depending on the property, the pest activity, and the products their pest control company uses. If you're seeing a lot of crickets around your home, you may want to consider starting with monthly treatments. Why crickets? Because crickets are a food source for scorpions. If your yard is providing a steady food supply, it may also be attracting scorpions. Controlling the insects that scorpions feed on can be just as important as treating for the scorpions themselves. Keep in mind that scorpions can be difficult to control with traditional pest sprays, so it's important to work with a pest control company that has experience treating for them. Are Scorpions More Active During Certain Times of the Year? Absolutely! Here in Arizona, scorpions are generally more active during the warmer months, particularly from spring through fall. When temperatures rise, they become more active as they search for food and shelter. During the cooler winter months, their activity usually slows down, although that doesn't mean they've completely disappeared. That's why some homeowners adjust their pest control schedule depending on the season and the amount of activity they're seeing. Why Does My Neighbor Have Scorpions but I Don't? Here's something I find particularly interesting about scorpions. You might have a neighbor who finds several scorpions every month, while you've lived next door for years and have never seen one. Scorpions tend to use areas that provide food, shelter, and suitable conditions. They may repeatedly travel along walls, fences, landscaping, and other protected areas. In some ways, it's similar to how deer tend to follow familiar paths. That doesn't mean scorpions follow one permanent trail or that your home will always be scorpion-free. But it does help explain why activity can be very different between two neighboring properties. And sometimes things change. For example, if someone nearby starts digging a swimming pool, removing landscaping, or doing major construction, that disturbance can affect scorpion habitat and potentially cause them to seek shelter elsewhere. So even if you've never had scorpions before, it's worth keeping an eye out when there's a lot of earth movement nearby. Does the Seller Have to Tell Me if They've Had Scorpions? This is an important question for anyone buying a home in Arizona. Our Arizona Seller's Property Disclosure Statement (SPDS) asks sellers about past or present problems involving scorpions and other pests. But here's something buyers should understand. Not every seller has actually lived in the home. Sometimes you're purchasing a rental property, an inherited home, or a property owned by an investor. In those situations, the seller may have limited knowledge about whether scorpions have been present. And even when the seller reports no known scorpion activity, that doesn't guarantee you won't encounter one after moving in. That's why I encourage buyers who are concerned about scorpions to ask questions and consider having a pest control professional inspect the property. Is Scorpion Pest Control Safe for Children and Pets? This is another question I hear, especially from families with young children or pets. Many pest control companies offer treatments designed for use around residential homes, including homes with children and pets. However, that doesn't mean every pesticide is harmless. Safety depends on the product being used, where it's applied, and whether the manufacturer's instructions are followed. A reputable pest control company should be able to explain what they're using, whether children and pets need to stay away from treated areas, and how long you should wait before returning. Don't be afraid to ask those questions. What Else Can I Do to Keep Scorpions Away? Besides regular pest control, there are some simple things homeowners can do: Keep crickets and other insects under control. Seal gaps around doors, windows, and plumbing openings. Check weatherstripping on exterior doors. Avoid leaving piles of wood, debris, or clutter near the home. Trim landscaping that provides hiding places near the house. Use a UV blacklight at night to check for scorpions, which glow under ultraviolet light. None of these steps guarantees you'll never see a scorpion, but together they can help reduce the chances. What If a Child Gets Stung by a Scorpion? Most scorpion stings cause pain and discomfort, but Arizona bark scorpions can be particularly dangerous for young children. If a young child is stung, contact Poison Control immediately at 1-800-222-1222 for guidance. If the child experiences difficulty breathing, severe muscle movements, or other serious symptoms, call 911. Frequently Asked Questions About Scorpions in Arizona How often should I spray for scorpions in Arizona? Many homeowners choose monthly or quarterly pest control treatments. The best schedule depends on the level of scorpion activity, the season, and the products being used. What months are scorpions most active in Arizona? Scorpions are generally most active from spring through fall, when temperatures are warmer. However, they can be found throughout the year. Does seeing crickets mean I have scorpions? Not necessarily. However, crickets are a food source for scorpions, so a large cricket population can make your property more attractive to them. Can scorpions get inside a well-maintained home? Yes. Scorpions can enter through small openings around doors, windows, plumbing, and other areas. Sealing entry points can help reduce the risk. Do Arizona home sellers have to disclose scorpions? Arizona's Seller's Property Disclosure Statement asks about known past or present scorpion problems. Sellers should disclose what they know, but some sellers, such as investors or heirs, may have limited knowledge of the property's history. Will regular pest control completely eliminate scorpions? Not necessarily. Regular treatments, controlling their food sources, sealing entry points, and reducing hiding places can all help, but no treatment guarantees a scorpion-free home. Should Scorpions Stop You From Buying a Home in Arizona? Not necessarily. I've worked with plenty of buyers who were very concerned about scorpions when they first started looking at homes, especially those relocating to Arizona. It's a reasonable concern, but it's also something you can investigate and manage. My advice is to ask about the property's history, pay attention to what you see around the home, and talk with a pest control professional if you're concerned. And if you're buying or selling a home in Mesa, Gilbert, Queen Creek, Apache Junction, or anywhere in the East Valley, we at Rover Realty are always happy to help you understand the questions worth asking before you make your move.
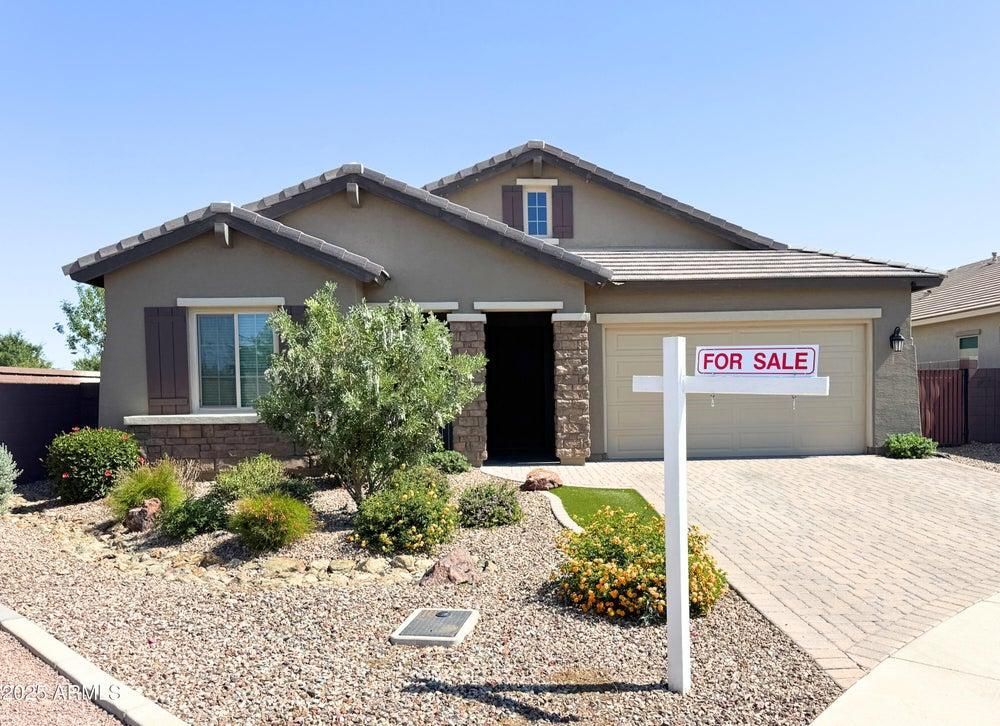
Does the name of the real estate brokerage really matter when selling your home? It's a fair question. Some real estate companies spend millions of dollars each year on billboards, television commercials, online advertising, and making sure their name is familiar to homeowners. But does that name recognition mean your home will sell faster or for more money? Not necessarily. After selling hundreds of homes across Mesa, Gilbert, Chandler, Queen Creek, Apache Junction, and the greater Phoenix area, I've seen excellent marketing from agents at large national brokerages and small independent companies. I've also seen some very poor marketing from both. The biggest difference is often not the company an agent works for. It's what that individual agent actually does to get your home sold. A Real Example From Three Listing Interviews Recently, we met with homeowners who were interviewing three different real estate agents to sell their property. Each agent had a very different plan. The first agent recommended painting the entire interior, moving all their belongings into storage, and paying thousands of dollars each month for professional staging. The sellers would also need to find temporary housing until their home sold. That's a lot of money to spend before even knowing how long the property might be on the market. Now, there are certainly homes where painting, professional staging, or even moving out makes sense. But those recommendations should be based on the home's condition, the competition, and the potential return on that investment. I later reviewed that agent's marketing and found that the listings I could see used photography without the additional marketing tools we typically provide. The second agent represented a very well-known brokerage with extensive television and billboard advertising. He explained that his company had a multimillion-dollar marketing budget that would help get their home sold. The homeowners asked a very good question: "How much of that marketing budget is actually spent marketing our home, rather than advertising your company to attract more sellers?" According to the homeowners, they didn't receive a clear answer. And that is an important distinction. A company can spend millions promoting its brand, but that doesn't necessarily mean it's spending that money to advertise your specific property to buyers. What We Did Differently When we arrived, we didn't start by telling the homeowners what their house was worth. Instead, we walked through the property, looked at its features and condition, discussed their plans, and answered their questions. We also shared examples of how Rover Realty markets homes, including: Professional photography and video tours Floor plans to help buyers understand the layout Custom yard signs featuring property photos YouTube videos and online marketing Professionally designed property brochures Complimentary light staging to help the home show its best We left them with our professionally bound seller's book, which explains our marketing process, introduces our team, and includes samples of the Arizona real estate contracts they could expect to see during the transaction. But there was one thing we didn't give them that day. A listing price. Why We Didn't Give Them a Price on the Spot The homeowners initially weren't thrilled that we wouldn't give them an immediate opinion of value. And I understand that. When you're interviewing agents, one of the biggest questions you have is, "What's my home worth?" You might also be wondering why we hadn't already researched the home and arrived with a price in mind. In this case, the sellers were the original owners. There were no prior listing photos for us to review, so much of what we knew before the appointment came from basic public records, such as the year the home was built and its square footage. But even if we had previous listing photos, our process wouldn't have changed. Photos don't tell the whole story. A home might look beautiful in pictures but have years of wear that isn't easy to see. There could be an unpleasant smell, an unusual floor plan, or something nearby that affects how buyers will feel about the property. On the other hand, the owners may have made beautiful upgrades that weren't reflected in older photos or public records. And sometimes it's simply the overall feeling you get when walking through a home. How the rooms connect, how much natural light comes in, and how the property compares to others you've seen. Those are things I want to experience in person before recommending a listing price. Once we've toured the property, we go back and study the market with a much better understanding of what we're comparing. We look at homes that have already sold to see what buyers have been willing to pay. But just as importantly, we look at the homes currently for sale because those are the properties we'll be competing against for the same buyers. A home doesn't sell in a vacuum. Buyers compare their options, and we need to understand how our listing will stand up against those choices. Only after putting all those pieces together do I feel comfortable recommending a price and a strategy to get the home sold. The next morning, we delivered a detailed digital report with comparable properties, our recommended pricing strategy, estimated selling costs, a net sheet, and a marketing plan specific to their home. We also included two simple sections: Our Homework and Your Homework. Their homework? Declutter some personal items and begin removing a few larger pieces of furniture they weren't planning to keep when they moved. That's it. No moving into temporary housing. No thousands of dollars in monthly staging fees. No recommendation to paint the entire interior. We would handle the light staging as part of our service. The husband called me the following morning and told me they were blown away by the time, research, and detail that went into our presentation. They chose Rover Realty to list their home. And while we're certainly happy to have earned their business, I think the bigger lesson is what happened during those three interviews. The homeowners weren't just choosing between three real estate agents. They were choosing three very different approaches to selling the same home. Does a Big Brokerage Have an Advantage? Sometimes, yes. Large brokerages may offer national referral networks, relocation connections, technology, and marketing resources that can benefit their agents and clients. But those resources are only valuable to a seller if the agent knows how to use them and actually puts them to work. It's also important to understand that agents within the same brokerage can operate very differently. One agent might invest heavily in professional photography, video, staging, and advertising. Another agent working under the exact same company name might provide only basic photos and an MLS listing. That's why I encourage sellers to interview the agent, not the logo. Don't Most Homes Go on the Same MLS Anyway? In the Phoenix area, most traditionally marketed residential listings are entered into the Arizona Regional Multiple Listing Service, better known as ARMLS. That means a properly listed home can be available to the real estate agents searching that system, whether the listing brokerage is a national franchise or a locally owned company. Many listings are also distributed to major home search websites. The brokerage name alone doesn't determine whether buyers can find your home. But what those buyers see when they find it can make a huge difference. Consider two similar homes listed at the same price. One has basic photos and a short description. The other has beautiful professional photography, a video tour, a floor plan, detailed property information, and marketing that highlights what makes the home special. Which one do you think is more likely to catch a buyer's attention? That's where an individual agent's marketing plan becomes important. Five Questions to Ask Before Hiring Any Real Estate Agent Whether you're interviewing an agent from a national company or a local independent brokerage, here are five questions worth asking. 1. Can you show me examples of homes you've recently marketed? Don't just look at the sold prices. Look at the photography, videos, property descriptions, and other materials used to attract buyers. 2. What marketing will you do specifically for my home? Ask what is included, what costs extra, and how the agent plans to reach buyers who might be interested in your property. 3. How much will I need to spend before listing? Some homes benefit from repairs or improvements, but every recommendation should have a clear purpose. Ask why the work is needed and whether the likely benefit justifies the cost. 4. How did you determine the recommended listing price? A good pricing recommendation should be supported by current market data, competing listings, and an understanding of your home's condition and features. 5. Who will actually be handling the sale of my home? Ask who will communicate with you, coordinate marketing, review offers, negotiate repairs, and help manage the transaction through closing. The Best Brokerage Is the One With the Right Agent and Plan There are excellent real estate professionals working for national brands, regional companies, and independent brokerages throughout Arizona. A recognizable name may give you confidence, but it shouldn't replace asking questions and reviewing the actual work. At Rover Realty, we are a locally owned brokerage, and we take pride in providing professional marketing, hands-on service, and a detailed plan for every home we represent. We don't expect sellers to hire us simply because we tell them we're good at what we do. We want them to see our work, understand our recommendations, and know exactly what we're going to do to help sell their home. Because when it comes to selling your home, the most important name isn't the one on the brokerage sign. It's the person responsible for getting the job done. Frequently Asked Questions Do large real estate brokerages sell homes faster than small brokerages? Not automatically. The home's price, condition, location, market competition, and individual agent's marketing strategy are generally more useful factors to evaluate than brokerage size alone. Will my home get less exposure if I list with a small real estate company? Not simply because the brokerage is smaller. Homes listed through ARMLS can receive broad exposure to participating real estate professionals and, when applicable, consumer home search websites. Additional marketing varies by agent. Do big real estate companies spend more money advertising my home? Some do, but a company's overall advertising budget may include promoting the brokerage itself, recruiting agents, and attracting future clients. Ask what advertising is specifically included for your property. Should I hire the agent who suggests the highest listing price? Not without reviewing the data. A higher suggested price doesn't mean a higher final sale price. Ask each agent to explain the comparable sales and market conditions supporting their recommendation. What should I look for when comparing real estate agents? Look at examples of their actual listings, the services they provide, their experience, communication plan, pricing strategy, and how they intend to market your specific home. Is an independent real estate brokerage a good choice for selling a home in Arizona? Absolutely, provided the agent has the experience, resources, and marketing plan to serve your needs. The quality of the individual agent and the services offered matters far more than whether the brokerage is independently owned or part of a national franchise. Thinking About Selling Your Home in Mesa or the East Valley? At Rover Realty, we're happy to show you exactly how we market homes and what we'd recommend for your property. Contact us to schedule a seller consultation and learn what goes into our personalized marketing plans. Rover Realty | Real Agents Helping Real People