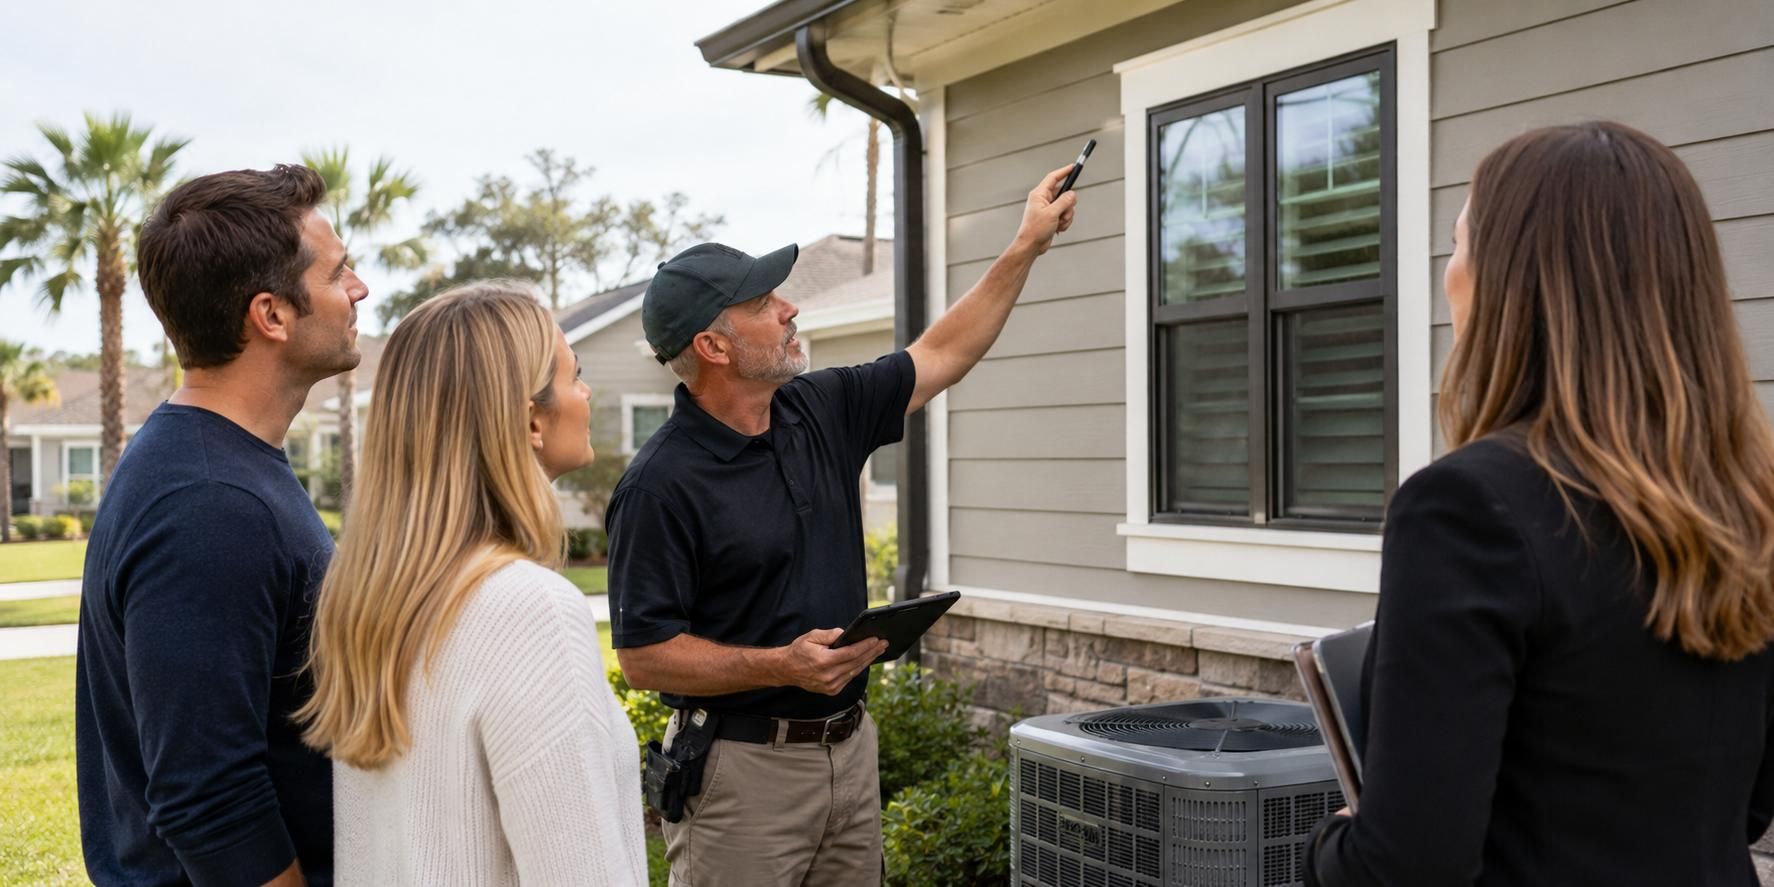
A client recently asked me a question that caught me off guard. One of his coworkers was buying a home and asked if he knew a home inspector and an appraiser . There are actually two very different questions hiding in there. First, why didn't his buyer's agent have home inspectors for him to consider? Second, buyers generally don't get to choose their appraiser at all. Let's start with the home inspection. Who Chooses the Home Inspector? The buyer does. As a real estate agent, I don't choose the inspector for my client. But I do think part of my job is making sure my buyers aren't left scrambling to Google "home inspector near me" after they are already under contract. I want my buyers to have options. Over the years, I've worked with many inspectors. That gives me the opportunity to see more than whether someone can complete an inspection. I get to see how they inspect and how they communicate their findings to the buyer. Those two things matter. Not Every Home Inspection Experience Is the Same A home inspector has an important job. Buyers need to know what they are purchasing, what may need attention and when another qualified professional should take a closer look. But how that information is presented matters too. I've seen inspectors who are excellent at explaining a concern, putting it into perspective and recommending further evaluation when something falls outside their area of expertise. I've also seen the opposite. I've seen inspectors make statements about issues outside their field of expertise. I've heard inspectors wander into legal or real estate advice that wasn't theirs to give. I've seen inspectors barely look into an attic access instead of actually inspecting the accessible attic space. And I've watched a relatively ordinary home maintenance item turn into something that sounded terrifying to a first-time buyer. That doesn't help the buyer make a better decision. I Don't Want an Inspector to Sugarcoat Anything This is important. I am not looking for inspectors who minimize problems to help keep a transaction together. Quite the opposite. If there is a major problem with the roof, electrical system, plumbing, structure or anything else they are qualified to inspect, I want my buyer to know about it. The inspector works for the buyer — not me. What I want is an inspector who can explain: Here's what I found. Here's why it matters. Here's how serious it appears to be. And here's when you should bring in a specialist for more information. There's a big difference between educating a buyer and frightening one. Why We Vet the Inspectors We Refer When we provide inspectors for a buyer to consider, we aren't simply handing them the first three names we found online. We want to know who we're sending into our client's future home. We look for inspectors who carry the appropriate licensing, bonding and insurance required for their work. Just as important, we pay attention to how thorough they are and how they communicate with clients. Do they actually inspect accessible areas? Do they stay within their scope? Do they explain concerns clearly? Do they recommend the appropriate specialist when something needs further evaluation? Do they give the buyer useful information without turning every maintenance item into a crisis? Those things matter to me because the inspection period is one of the most important parts of buying a home. The Buyer Still Gets to Choose Providing referrals doesn't mean the buyer has to use one of them. Buyers are free to research inspectors, read reviews and select someone else. My job is to make sure they have good information and good options. In fact, throughout a real estate transaction, buyers may need several different professionals depending on the property — home inspectors, roofers, HVAC companies, electricians, plumbers, pool inspectors, septic professionals and others. An experienced agent should be prepared for that. You shouldn't have to build your entire real estate team from scratch after you're already under contract. What About the Appraiser? That's where this client's question gets even more interesting. The coworker was also looking for an appraiser . That's a completely different process. If you're obtaining a mortgage, you generally don't get to call an appraiser you like and hire that person to appraise the home for your loan. There are independence rules surrounding the appraisal process, and the lender handles ordering the appraisal through its required process. And there's another question buyers frequently don't realize they should ask: When should the appraisal be ordered? In many transactions, I prefer for my buyers to get through their inspection period before spending money on the appraisal when the timing of the contract and loan allows us to do so. There's a very practical reason for that. If we discover something during inspections that causes the buyer to cancel the contract within their contractual rights, I don't want them to have already spent hundreds of dollars on an appraisal they no longer need. That's an entirely different conversation — and one worth having before you buy a home. We'll tackle that one next. FAQs Can my Realtor choose my home inspector? The buyer chooses the inspector. Your agent can provide inspectors for you to consider, but you can research and select your own as well. Why would a Realtor recommend more than one inspector? Providing several options allows the buyer to compare availability, pricing, services and reviews while still benefiting from the agent's experience working with inspectors during past transactions. Should I automatically use the cheapest home inspector? Price matters, but it shouldn't be the only consideration. You're paying someone to evaluate one of the largest purchases you'll probably ever make. Experience, thoroughness, communication and the services included in the inspection can be just as important. What if the home inspector finds something outside their expertise? Depending on the issue, the inspector may recommend further evaluation by an appropriate specialist, such as a roofer, electrician, plumber, HVAC contractor or structural professional. Do I choose the appraiser when buying a home? Generally, not when an appraisal is being completed for a mortgage. The lender orders the appraisal through a process designed to maintain appraiser independence. Is a home inspection the same thing as an appraisal? No. A home inspector evaluates the home's condition and systems. An appraiser develops an opinion of the property's value for the lender. They serve very different purposes. Rover Realty Real agents helping real people throughout Mesa, Gilbert, Queen Creek, Chandler, Apache Junction and communities across the Phoenix East Valley.
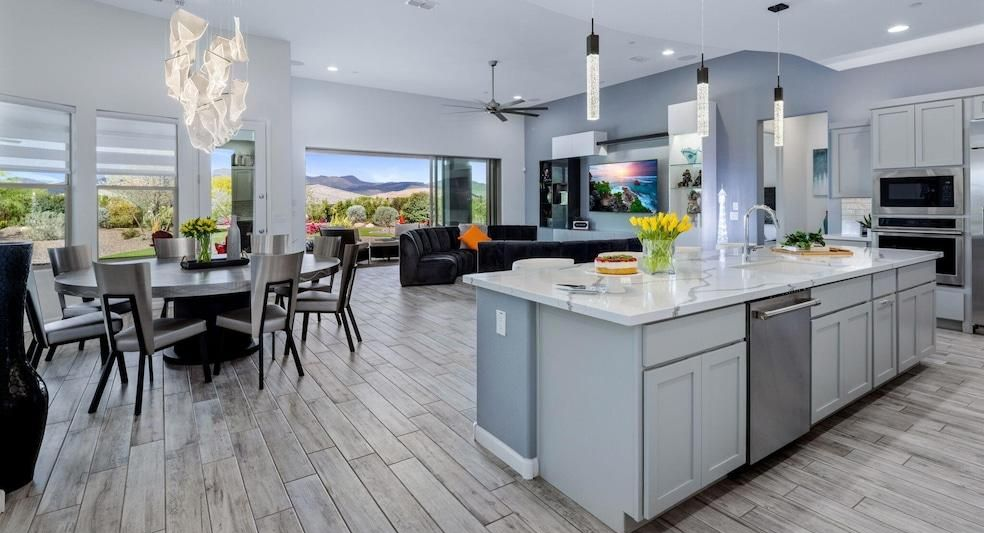
Sellers ask me this all the time: “Should I leave the refrigerator, washer and dryer? Will that make my house worth more?” Usually, the answer is no — but that doesn't mean leaving them can't help sell the house. There is a difference between something adding value to your home and something making your home more attractive to a buyer. And appliances are a great example. Which Appliances Normally Stay With the House? First, let's clear up something that causes more confusion than it should. In a typical Arizona resale transaction, certain items are already included with the home unless the contract says otherwise. The Arizona REALTORS® purchase contract specifically addresses fixtures and personal property that are included in the sale. Built-in appliances and the free-standing range/oven are among those items. So when I see someone advertising that the stove or attached microwave “conveys with the house,” I usually smile a little. Those aren't exactly bonus items. They have been addressed in our contracts for many, many moons. The refrigerator, washer and dryer are different. Those are generally treated as additional personal property. They can be included with the sale, but they don't automatically become part of the house just because they're sitting there. Arizona REALTORS® contract guidance specifically discusses the refrigerator, washer and dryer as additional personal property that can be included in the transaction. Do a Refrigerator, Washer and Dryer Add Value to My Home? Typically, not to the actual value of the real estate. You might have spent $5,000 or $8,000 on a beautiful appliance package, but that doesn't mean an appraiser is going to add $5,000 or $8,000 to the value of your house because you're leaving it behind. In fact, Arizona REALTORS® guidance explains that when additional personal property such as the refrigerator, washer and dryer is included under the purchase contract, it is transferred with no monetary value . But here's where sellers sometimes stop listening too soon. Something doesn't have to add appraised value to help us sell your home. Sometimes Appliances Are a Marketing Tool Let's say we're selling your home in an area with a lot of new construction. Now we're competing against builders offering buyers incentives that a resale seller simply can't match dollar for dollar. The builder may be advertising a lower interest rate, money toward closing costs and brand-new appliances. I've even had a buyer receive two years of HOA dues paid by a builder. Suddenly, a resale home where the buyer also needs to purchase a refrigerator, washer and dryer can feel like one more expense. If my seller already plans to replace those appliances at their next house or simply doesn't care about taking them, including them can give us another selling point. Refrigerator, washer and dryer included. Does that suddenly make a $500,000 house worth $510,000? No. Could it make our house more appealing to a buyer comparing several homes at roughly the same price? Absolutely. That's where appliances can have value without necessarily adding to the home's market valu e. Sometimes I Would Rather NOT Advertise Them This is where strategy comes into play. If a seller is willing to leave the refrigerator, washer and dryer, we don't necessarily have to advertise that from day one. Sometimes I'd rather keep those appliances in our back pocket. Maybe a buyer makes an offer and wants something the seller doesn't particularly want to give them. Instead of immediately moving on price or agreeing to another concession, we may have something else available to negotiate. Would including the refrigerator, washer and dryer help us bridge that gap? Maybe. If those appliances weren't already promised with the house, they can become another piece of the negotiation. That's why my answer isn't automatically, “Yes, leave them,” or “No, take them.” I want to know what we're competing against, what matters to the seller and where those appliances give us the most leverage. Luxury Homes Can Be Different There are also situations where taking an appliance would make very little sense. A luxury kitchen with a built-in refrigerator is an obvious example. The refrigerator may be designed into the cabinetry and feel like part of the kitchen itself. The same can be true with a stackable washer and dryer designed specifically for a laundry area inside a primary closet or another custom space. In those situations, removing the appliance could actually leave behind a space that feels unfinished or creates a problem for the next owner. That's very different from a standard freestanding refrigerator that can easily move with the seller. Don't Decide Based Only on What You Paid for Them This is probably the biggest point I want sellers to understand. What you paid for an appliance isn't necessarily what it's worth to the sale of your house. A $3,500 refrigerator doesn't automatically make your home worth $3,500 more. But if including that refrigerator makes your home more competitive with the house down the street — or with a builder offering a shiny appliance package — it may still be very useful. That's why I look at appliances as part of our marketing and negotiation strategy , not simply as a dollar-for-dollar home improvement. Before we list, we'll talk about what stays, what goes and what might be better saved as a negotiating tool. Sometimes the refrigerator is just a refrigerator. And sometimes it's one more reason for a buyer to choose your house. FAQs About Selling a Home With Appliances Does the refrigerator automatically stay when I sell my Arizona home? Not necessarily. A refrigerator is commonly handled as additional personal property in the Arizona REALTORS® purchase contract. If it is going to be included, the contract should clearly reflect that. Do the washer and dryer have to stay? No. Like the refrigerator, a washer and dryer are commonly treated as additional personal property and can be included in the transaction if agreed upon. Does the stove stay with the house? Under the Arizona REALTORS® residential resale contract, the free-standing range/oven is among the listed items included with the sale unless otherwise excluded in the contract. Built-in appliances are also included. Will leaving expensive appliances increase my appraisal? You shouldn't assume that the price you paid for the appliances will be added to your home's appraised value. Arizona REALTORS® contract guidance states that additional personal property such as an included refrigerator, washer and dryer transfers with no monetary value under the contract. Is it better to advertise that appliances are included? Sometimes. If we're competing against new construction or trying to make the home especially attractive to first-time buyers, including appliances may be a strong marketing point. In other situations, we may choose not to advertise them upfront and keep them available as part of a later negotiation. What if I want to take an appliance that would normally stay? Tell your real estate agent before the home goes on the market. Items that would otherwise be included should be clearly addressed so buyers understand what is and isn't part of the sale. Arizona REALTORS® specifically advises sellers to review the fixtures and personal-property provisions before receiving an offer and identify anything they do not intend to transfer. Selling a Home in Mesa or the East Valley? Little decisions like whether to include a refrigerator probably aren't going to determine the value of your home by themselves. But when we're competing for buyers, the little things can absolutely affect how your home is positioned. At Rover Realty, we look at the entire picture — your competition, nearby new construction, buyer incentives, pricing, presentation and the items we may be able to use during negotiations. The goal isn't to give everything away. It's to figure out what actually helps us get your home sold while protecting the things that matter most to you.
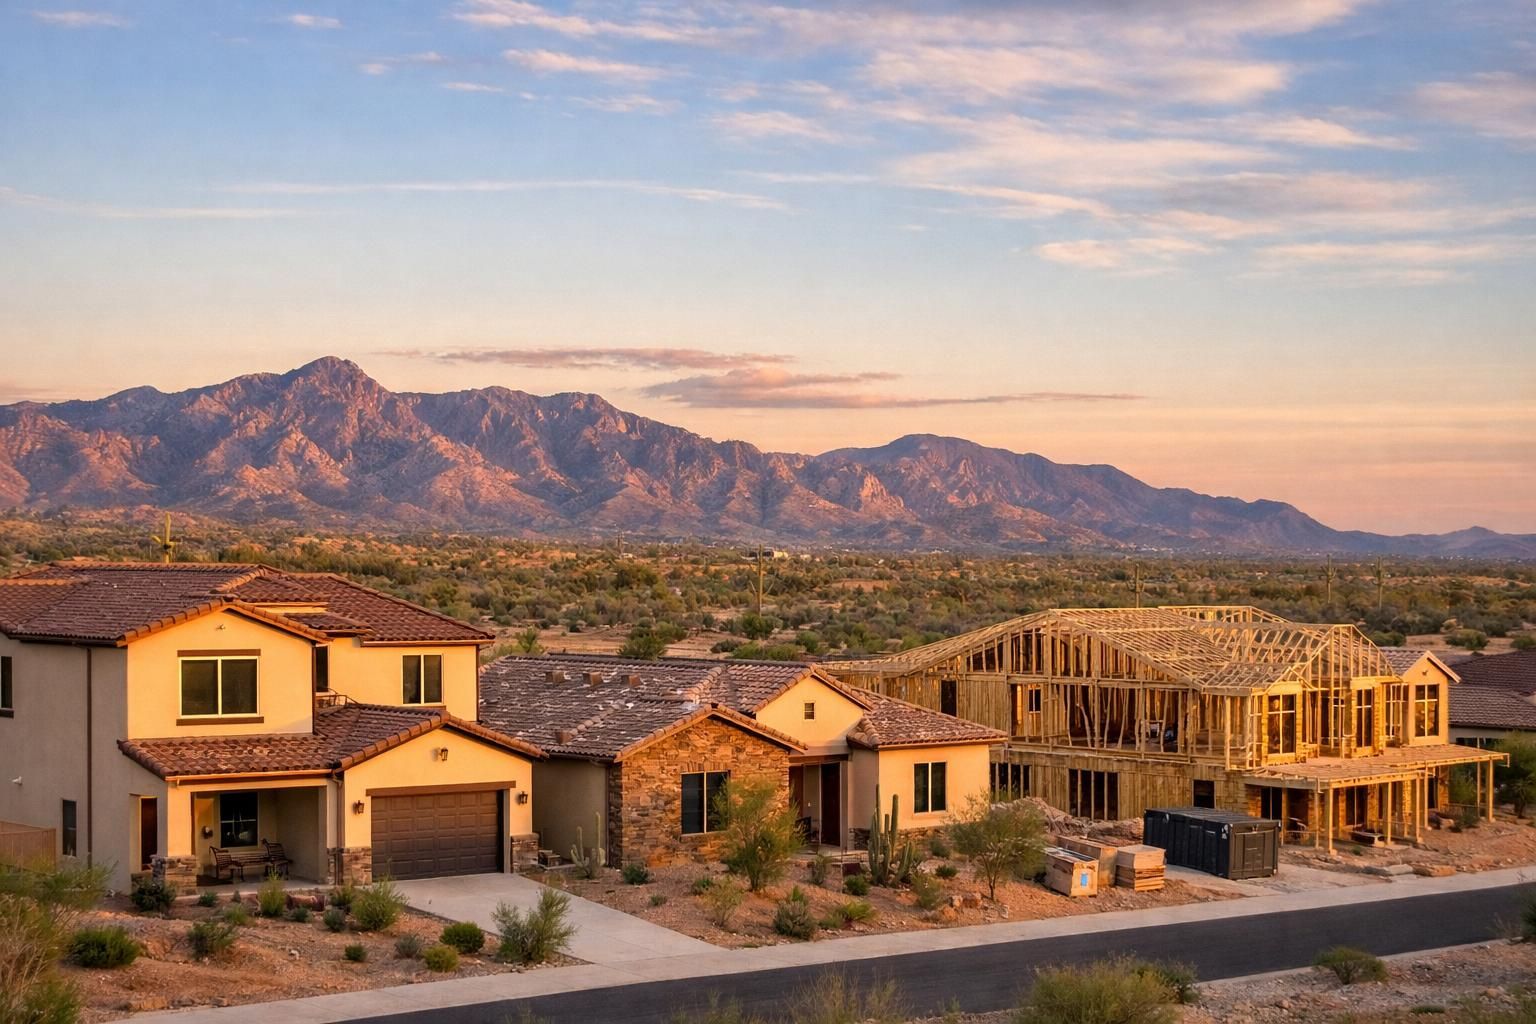
If you live near new construction, you may have noticed something that seems strange. A resale home in your neighborhood has been sitting on the market for weeks — maybe months — while the builder down the street keeps selling homes. You might look at that house and think: What's wrong with it? Sometimes, absolutely nothing. The problem may be that the seller isn't just competing with the other resale homes in the neighborhood. They're competing with the builder. And that changes everything. The Builder May Be the Biggest Competition This is something many homeowners don't realize until they're ready to sell. Builders may be offering buyers incentives such as: Below-market interest rates Closing cost assistance Appliances Design or upgrade incentives HOA incentives Other financing or move-in specials We even had a client purchase a new construction home where the builder paid two years of HOA dues upfront. These offers change frequently and vary by builder, community, home and financing program. But if I'm helping someone sell near active new construction, I want to know what those builders are offering. Because buyers know. And they're comparing those offers to the resale home. Buyers Aren't Always Shopping by Price This is probably the biggest thing I wish more resale homeowners understood. Many buyers aren't shopping based only on the price of the house. They're shopping based on the monthly payment. Here's an example of just how much a builder's lower interest rate can change the comparison. Let's say a buyer is considering a $475,000 resale home at a 7% interest rate. Down the street, a builder has a $550,000 new home and is offering qualified buyers a 4.25% rate. Assuming a 30-year fixed mortgage and 5% down, here's what the principal-and-interest portion of those payments would look like: $475,000 Resale $550,000 New Build Purchase Price $475,000 $550,000 Down Payment (5%) $23,750 $27,500 Loan Amount $451,250 $522,500 Interest Rate 7.00% 4.25% Principal & Interest About $3,002/mo. About $2,570/mo. The new home costs $75,000 MORE, yet its principal-and-interest payment is approximately $432 LESS per month. That's a big deal. A homeowner with a $475,000 resale may look at that $550,000 new build and think: "That's not my competition. Their house costs $75,000 more than mine." But the buyer may be thinking: "I can buy the brand-new house and have a lower monthly principal-and-interest payment." Now we have a completely different sales challenge. These numbers are for illustration and compare principal and interest only. They don't include property taxes, homeowners insurance, mortgage insurance, HOA fees or other costs that affect the total monthly payment. Builder financing incentives also have specific qualifications and can change. Buyers should always get actual payment information from their lender. And Then the Buyer Walks Into the Model Home Now add another layer. Model homes are designed to sell houses. The furniture is beautiful. The finishes are current. The lighting is right. The rooms are staged. Everything is designed to help buyers picture themselves living there. Then that buyer walks into a resale home. If it's cluttered, dark, dated or has obvious deferred maintenance, the difference can feel much larger than it really is. That's why presentation matters even more when we're competing against builders. We aren't trying to make a resale home look brand new. We're trying to make sure it looks like a strong alternative to brand new. But Resale Homes Have Advantages Too New isn't automatically better. A resale home may already have a finished backyard, mature landscaping, window coverings, ceiling fans, appliances, upgraded lighting, storage, a pool or thousands of dollars in improvements that aren't necessarily included in the builder's advertised price. It may have a larger lot. It may be in a finished section of the neighborhood without years of construction around it. It may have a location or homesite the builder can no longer offer. Those things have value. But buyers need to see and understand that value. That's where marketing becomes incredibly important. So Why Is That Resale Home Still Sitting? It isn't always because the price is too high. Sometimes the home wasn't prepared well enough. Sometimes the photos don't compete with what buyers are seeing online from the builder. Sometimes there isn't enough marketing beyond putting the property in the MLS. Sometimes nobody has clearly shown buyers what is already included in the resale home. And sometimes the pricing strategy was based almost entirely on other resale sales without paying enough attention to what a buyer can purchase brand new nearby. Usually, it's not one single thing. It's the entire package. Resale Sellers May Have More Options Than Buyers Realize Builders are very good at advertising their incentives. Resale sellers don't have a giant sign at the entrance to the neighborhood advertising theirs. Depending on the financing and terms negotiated in the transaction, a resale seller may be willing to provide concessions that a buyer could potentially use toward allowable closing costs or an interest-rate buy-down. But many buyers don't even know that may be an option. That's another reason positioning and marketing matter. We can't assume buyers will figure out every advantage of the resale home on their own. I Often Help Sellers When the First Try Didn't Work I regularly talk with homeowners whose first attempt at selling didn't produce the result they expected. Sometimes the listing expired. Sometimes the seller canceled it. Sometimes they're simply trying to figure out what they should do differently before trying again. My first question isn't: "How much should we reduce the price?" It's: "Why didn't the home sell?" Those are two very different conversations. If the home is competing with new construction, I want to understand what buyers were comparing it against. What were nearby builders offering? How did the home present online? Was it clean and ready for buyers? Did the photography help it compete? Was minor staging needed? Did buyers understand the value of the improvements already included with the home? Was there enough online exposure? Did the pricing make sense once builder incentives were taken into consideration? Only then can we build a strategy for bringing the home back to market. Selling Near Builders Means We Can't Cut Corners We are getting resale homes sold in areas with heavy new construction. But these are not the listings where I want to stick a sign in the yard, take a few photos and hope someone eventually comes along. The home needs to look as clean and turnkey as reasonably possible. We use minor staging when it helps. We use professional photography, floor plans and video to help buyers understand the property before they ever get in the car. We pay attention to online placement and how the home's advantages are presented. Because your first showing isn't necessarily happening inside your house anymore. It's happening on someone's couch. That buyer may have your home open in one browser tab and the builder's website open in another. Our marketing needs to give them a reason to click on yours. Before You List — Or Before You List Again If you're thinking about selling a home near new construction, don't just look at what the house next door sold for six months ago. We need to look at what your buyer can purchase today. And if your home was already on the market and didn't sell, don't automatically assume the only solution is a major price reduction. First, let's figure out what happened. I look at the resale competition, nearby builders, current incentives, condition, presentation, pricing and marketing to determine where the property may have lost buyers — and what we can do differently the next time around. Sometimes the home doesn't need a dramatically lower price. It needs a different strategy. Frequently Asked Questions Why are resale homes taking longer to sell near new construction? Builders may be competing for the same buyers with below-market financing, closing cost assistance, warranties, appliances and other incentives. That can make new construction attractive even when its purchase price is higher. Can a more expensive new home actually have a lower monthly payment? Yes. Interest rates can make a significant difference. In our example, a $475,000 resale at 7% had an estimated principal-and-interest payment of about $3,002 per month. A $550,000 new home at 4.25% was approximately $2,570 per month using the same 5% down payment. That's roughly $432 less per month even though the new home costs $75,000 more. Taxes, insurance, mortgage insurance, HOA fees and other costs still need to be considered. Does a resale seller have to lower the price to compete with a builder? Not necessarily. Price is important, but so are condition, presentation, included improvements, lot, location and marketing. I want to understand the entire competitive picture before recommending a pricing strategy. My home was listed before and didn't sell. Does that mean it was overpriced? Not automatically. Pricing could have been a factor, but I also want to look at presentation, photography, marketing, buyer feedback, showing activity and competition from both resale homes and builders. Should nearby builder incentives be considered when pricing my resale home? Absolutely. Buyers are comparing those options whether the resale seller realizes it or not. Knowing what the builders are offering helps us understand the competition we're actually facing. Can Rover Realty help if my home was previously listed with another agent? Yes. I often work with sellers who are preparing to try again. I start by looking at what happened during the previous listing and what has changed in the market. From there, we can build a new strategy around the home's current competition rather than simply repeating the same approach. Rover Realty | Real agents helping real people.